The financing model for large international film productions in Spain has received a significant legal backing. The Second Section of the Contentious-Administrative Chamber of the National Court ruled this May on a judgment that amends the inspection strategy of the Tax Agency. The court determines that Economic Interest Groups (AIE) structured as financial co-producers have the full right to consolidate tax deductions for investments in national territory, nullifying the settlements that sought to classify these vehicles as mere artificial structures for tax evasion.
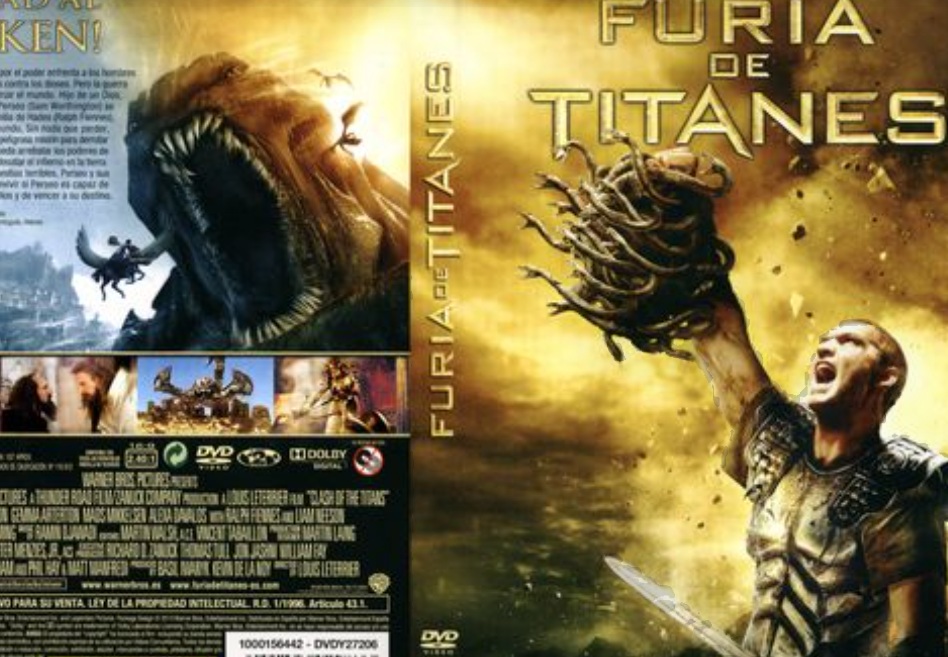
The ruling, with Judge Francisco Pleite Guadamillas as the rapporteur, upholds the appeal filed by an oil company in Las Palmas. The claimant company held a 1.39% stake in the entity Furia de Titanes II, AIE, a vehicle constituted to channel investment in the production of the eponymous feature film by Warner Bros, shot partially in the Canary Islands. The judicial resolution annuls the previous agreement of the Central Economic-Administrative Court (TEAC) and restores deductions corresponding to the fiscal years 2012 and 2013, which jointly amounted to 314,094.13 euros, also obliging the State to return the late payment interest paid by the taxpayer.
The Conflict Over the Conceptual Sovereignty of Tax Law
The central controversy of ordinary procedure 697/2020 lay in the definition of the legal concept of ‘film producer’. The State Legal Service defended the existence of an autonomous tax concept, independent of the sectoral legislation of cinema. According to the fiscal thesis, the Spanish AIE lacked real initiative, operational control, and assumption of direct commercial risks, since the co-production contract delegated day-to-day executive decisions to American subsidiary corporations of Warner Bros (Cott Productions LLC, Dover Distributions, and Gorgon Productions). The Tax Agency argued that the local group merely provided documentation and administrative management support during filming in the Canary Islands.
The National Court rejects this interpretation based on the principle of unity of the legal system. The court states that, while Tax Law enjoys autonomy to explicitly delineate its own categories —as is the case with the figure of the entrepreneur for VAT purposes— it cannot create concepts ex novo without normative justification when there exists applicable sectoral regulatory legislation. Consequently, the Chamber refers to the Intellectual Property Law and the Cinema Law to conclude that the figure of the producer accommodates various modalities, including that of co-producer, executive producer, and financial producer.
Validation of the Sector Structure and Legal Certainty
The judicial analysis validates the clauses of the co-production contract executed in public in February 2011. The ruling confirms that the Spanish subsidiary assumed the ownership of the intellectual property rights over the audiovisual work for a specific geographical market and accounted for the asset as intangible fixed assets. The Chamber emphasizes that the fact that a multinational holds a majority position and reserves the final editing rights does not undermine the local entity’s producer status, which managed the risk policies of the production on Spanish soil, cast supporting actors, and contracted fixed technical teams through the local producer Sur-Film Production & Services.
The court grounds its decision on the need for coordination among the different bodies of the General State Administration. The ruling recalls that the Institute of Cinematography and Audiovisual Arts (ICAA) had formally registered the AIE in the Film Companies Registry and that the Culture Department of the Government of the Canary Islands issued the official certificate of the Canarian audiovisual work.
The National Court rules that the Tax Inspection cannot issue a criterion that diverges from that of the competent sectoral bodies, invoking the principle of legitimate expectation and Article 39.4 of the Common Administrative Procedure Law, which requires respect for final acts issued by other branches of public administration. The ruling imposes the legal costs on the defendant Administration and opens the way for an appeal to the Supreme Court. This ruling consolidates the legal certainty of the tax incentives provided in the Corporate Tax for attracting international shoots, affirming the role of Economic Interest Groups as legitimate investment tools in the entertainment industry.