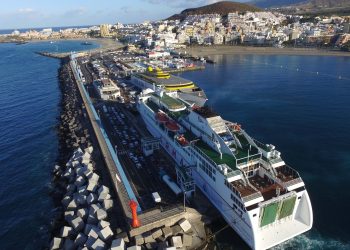
An increase of 10% in maritime transport costs in just 24 hours is not an abstract figure in a continental region. In the Canary Islands, where more than 85% of consumer goods arrive by ship, that percentage becomes a silent multiplier of inflation. The logistical structure of the archipelago —based on rapid inventory turnover and high external dependence— amplifies any disruption in crude oil prices.
The system operates with tight margins and high replenishment frequency. Large chains and importers work under just-in-time schemes, reducing storage to contain financial and space costs. When transport costs suddenly increase, the transfer to the final price occurs more quickly than in economies with greater local production or stock capacity.
Gasoline 95 and 98, as well as diesel, constitute the highest risk category. The exposure is direct: the international price of crude impacts the raw material, while the increase in bunkering costs raises logistical supply costs. In an island market, where land transport almost entirely relies on imported fuel, the effect is twofold. First, the pump price rises; then, distribution costs increase.
Unlike other products, fuel does not allow for immediate substitution or delay in replenishment. Demand elasticity is limited in the short term, facilitating the almost automatic transfer of the extra cost.
Imported fruits, vegetables, and meats form the second critical block. These are perishable goods that require constant cold chain management and predictable transit times. If maritime routes are extended —for example, due to strategic diversions in international trade— the impact is not limited to freight costs: energy expenses for refrigeration, insurance, and inventory management also increase.
Furthermore, uncertainty in timelines forces the reinforcement of safety stocks, breaking the financial equilibrium of the rapid turnover model. The result is direct pressure on the final price and, in specific cases, the risk of temporary shortages.
Rice, pasta, and sugar present a different vulnerability. They are not perishable and do not depend on the cold chain, but their low unit value and high volume make them extremely sensitive to container costs. When transport represents a significant percentage of the total price, any increase erodes margins or is passed on to the consumer.
In this segment, the key is not urgency but scale. The logistical system in the Canary Islands relies on volume economies; if the cost per TEU increases steadily, the impact is spread over thousands of units, accumulating generalized inflationary pressure. Vulnerability does not stem from poor management, but from the very nature of being an island. Specialization in services and tourism has historically reduced local production of basic goods, reinforcing dependency on maritime transport. In contexts of energy stability, the model is competitive. Under geopolitical tension, it becomes fragile.
The question for the regional government is not just how to contain the immediate impact, but whether to strengthen strategic reserves or incentivize local production in specific sensitive segments. The 10% cost overrun may be circumstantial. Structural exposure, on the other hand, is permanent.