Kosmos Energy, a traditional customer of the ports of Tenerife, has achieved a significant milestone in its financial consolidation roadmap. S&P Global Ratings has upgraded the company’s credit rating from the speculative ‘CCC’ level to ‘B-‘, a decision that underscores the positive impact of active debt management and a markedly favorable energy price environment. This move, announced on May 14, 2026, positions the Dallas-based company on a path to stability, leaving behind the operational vulnerability that marked its previous financial year.
The central thesis of this improvement rests on the strength of oil prices. With Brent crude pricing near 100 dollars—figures that greatly exceed early-year conservative forecasts—the company has seen its revenues surge. This factor, combined with a record quarterly production of 75,000 barrels of oil equivalent per day (boe/d), has allowed Kosmos to accelerate its deleveraging strategy. While in 2025 the firm reported a debt-to-EBITDA ratio of 5.8x, management projects to bring this indicator down to below 2.5x by the end of 2026, marking a structural change in its balance sheet.
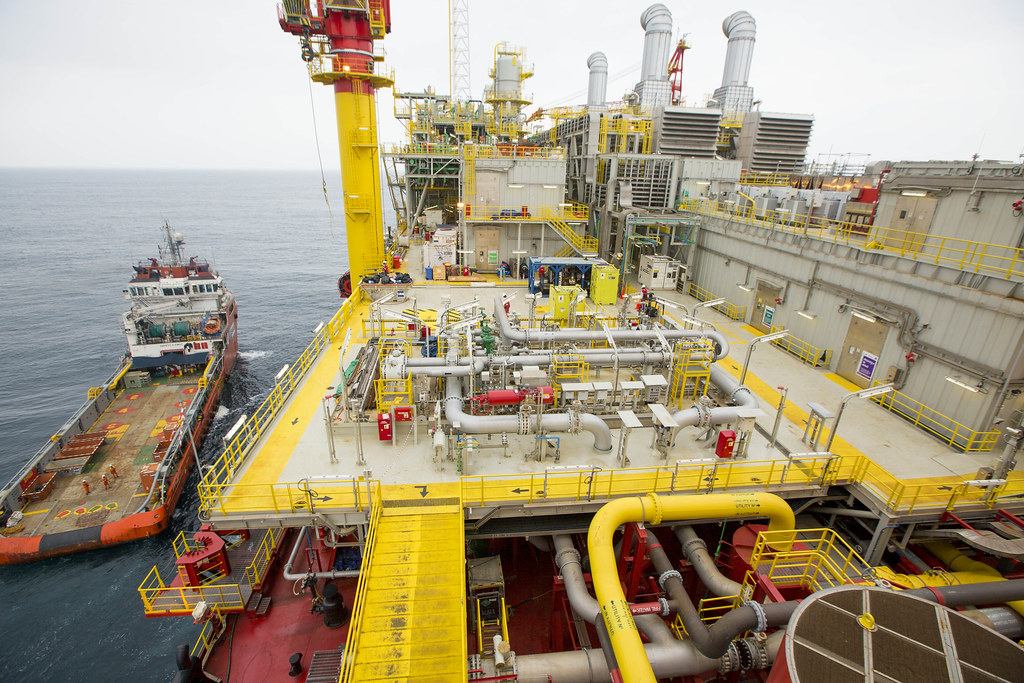
The fundamental pillar of this operational growth lies in the Greater Tortue Ahmeyim (GTA) project, a strategic bet located off the coasts of Mauritania and Senegal. This complex, which already contributes 23% of the group’s total production, has become the crucial asset for its future cash generation. In a high-price environment, the increase in LNG production solidifies Kosmos as a key player in West Africa’s energy infrastructure. The company is significantly mitigating unit costs by eliminating the startup burdens that weighed down its accounts in previous periods.
The financial architecture of this change has been intense. Since January 2026, Kosmos has executed a series of tactical transactions, highlighted by the raising of 350 million dollars in senior secured bonds linked to its GTA assets and the divestiture in Equatorial Guinea. This latter operation, valued at 180 million dollars, is seen by analysts as a surgical exit from high-cost operational assets, allowing the firm to redirect capital towards reducing its RBL credit line and developing lower-cost projects in the Gulf of Mexico, such as the Tiberius field.
Despite the optimism generated by this improvement in credit profile, the stable outlook granted by S&P incorporates caution. The company still faces periodic liquidity tests and bond maturities in 2028, keeping alive the need for uninterrupted cash flow operating. The success of Kosmos will depend on its ability to sustain operational execution at Jubilee, Ghana—the current engine of its production volume accounting for nearly half of the total—and its ability to navigate the volatility in oil contractual hedges that delay the complete realization of gains.
The market watches closely as Kosmos navigates this new phase. The exploratory alliance signed in February with Shell in the Gulf of Mexico suggests that the company has not abandoned its growth ambitions, albeit under a more disciplined shared-risk model. If the firm can maintain its FFO/debt ratio between 25% and 30%, it will have definitively overcome doubts about its sustainability. For now, the verdict is clear: the era of strict dependence on external conditions for survival seems to have concluded, paving the way for a phase of operational maturity and greater financial solvency.